austin
2026-10-23
NextDC Fell 44% on a Delay. Here's What It Teaches Data Center REIT Dividend Investors
- NextDC fell 44% on a profit warning, erasing A$3.1 billion in market value, after power grid delays at its M3 facility.
- Over five years, Digital Realty returned 29.2% and Equinix 28.1% with distributions reinvested. These are slow compounders, not yield plays.
- Over the last year the two split: Equinix returned 17.4% and Digital Realty 2.0%, both with distributions reinvested.
- NextDC suggests the risk to a data center payout may sit in power, timing and the balance sheet, more than in the yield number.
NextDC's share price fell 44% after its October 21 profit warning, wiping out A$3.1 billion in market value. The trigger was a power line upgrade that couldn't be finished on time.
My read: for anyone holding data center REITs for income, the yield is the least informative number on the screen. What decides whether the payout holds is whether new capacity gets powered and billed on schedule, and whether the balance sheet can absorb it when it doesn't.
One delayed site cut NextDC's EBITDA outlook by about a third
NextDC is an Australian data center operator, and on October 21, 2026 it cut its outlook. The company pointed to delays at its M3 campus in Melbourne, which has 225MW of total power capacity. The grid upgrade it needs is now expected to restart in February 2027, and A$140 million of contracted revenue came out of the fiscal 2027 outlook.
The revised guidance shows how much one site can matter. Fiscal 2027 underlying EBITDA is now expected at A$245-265 million, down from A$385-410 million. Net revenue guidance fell to A$475-500 million from A$615-640 million. For scale, fiscal 2026 EBITDA was A$248.8 million and net revenue was A$405 million. In other words, the delay turns what was supposed to be a growth year into roughly a flat one on EBITDA.
The mechanic is simple. Revenue only starts when new capacity is powered, so a late grid connection pushes income into the future. The company's response was to cut capital spending guidance and freeze new development projects. Dividends get paid out of what is left.
The US names look steady over five years, but they aren't yield stories
I pulled Digital Realty (DLR) and Equinix (EQIX) to see what the same sector looks like in the US. Over five years, October 22, 2021 to October 22, 2026, DLR returned 29.2% with distributions reinvested, a 5.3% annual rate. EQIX returned 28.1%, or 5.1% a year.
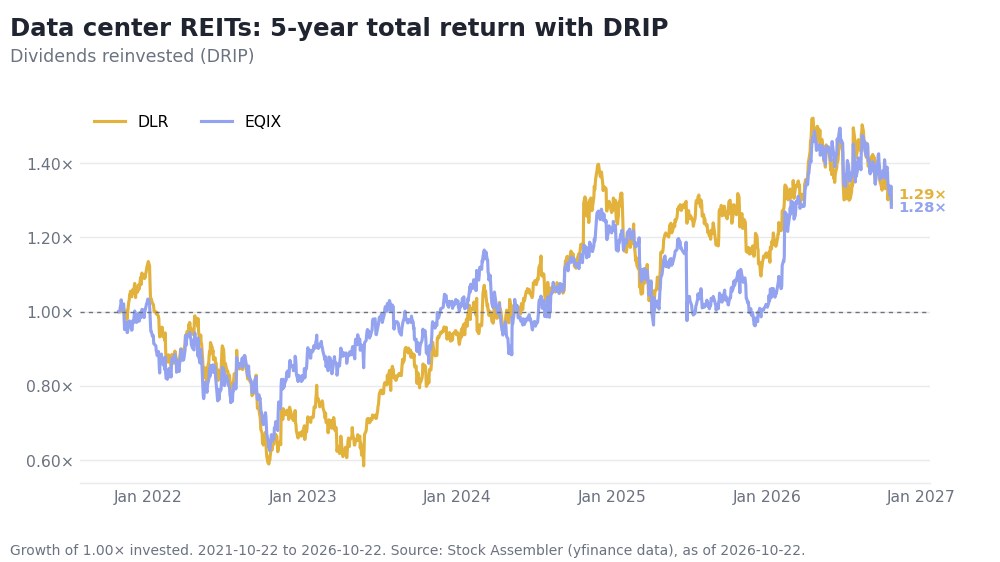
Growth of a dollar invested with distributions reinvested, October 22, 2021 to October 22, 2026, DLR and EQIX. Data: Stock Assembler (yfinance).
Both stocks sank through 2022 and into early 2023, then recovered. DLR's maximum drawdown was -51.1% on price alone, and EQIX's was -40.4%. Both paid quarterly distributions throughout, 20 in total. But holders who needed the cash flow lived through a long stretch where the share price was well under what they paid.
The yields explain why. DLR's trailing 12-month yield is 2.9%, paying $4.88 per share. EQIX yields 2.1%, paying $20.17 per share. Nobody buys these for current income. Most of the long-run return has come from price growth, and price growth depends on exactly the thing NextDC just stumbled over: getting new capacity built and filled.
The last year shows how different two data center REITs can be
Over the last 12 months the two diverged sharply. EQIX returned 17.4% with distributions reinvested, and DLR returned 2.0%. On price alone, EQIX rose 14.9% while DLR slipped 0.9%.
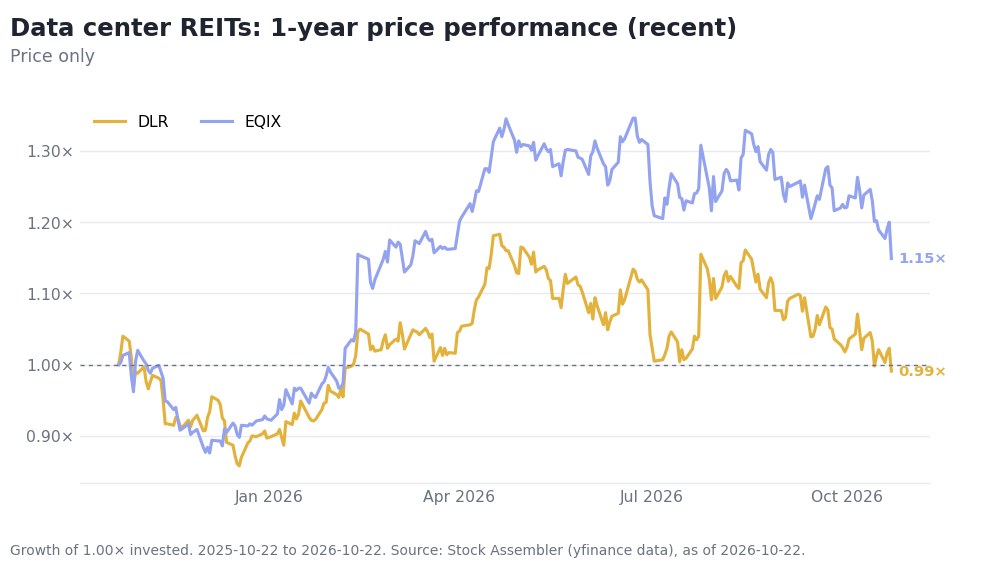
Growth of a dollar invested, price only, October 22, 2025 to October 22, 2026, DLR and EQIX. Data: Stock Assembler (yfinance).
The chart shows the two lines tracking each other until early 2026, then EQIX pulling ahead from spring, finishing at 1.15x against DLR's 0.99x. DLR ended the year slightly under where it started. Both were volatile, with annualized volatility of 27.6% for DLR and 25.8% for EQIX. Same sector, same AI demand story, very different outcomes. I can't tell you from price data alone why. Differences in tenant mix, geography, build schedules and funding are the usual suspects, and that is the point: there is no single data center REIT dividend.
You can run this comparison on any pair of funds in Stock Assembler's Compare Tickers tool.
What the data doesn't tell us
Nothing in this data says a US data center REIT dividend is in danger. Neither paid a special distribution in the last 12 months, and both have paid every quarter for five years. NextDC is one operator with one troubled site, and I haven't seen its dividend history, so I won't claim its payout is at risk.
What the case does show is that this sector can reprice violently on a schedule problem. The fall was 44% after one profit warning. A 2.9% or 2.1% yield doesn't cushion anything like that.
What to check before you rely on the payout
Price history won't answer these questions, so go to the filings:
- AFFO payout ratio. How much of the cash the company generates goes out as distributions? A lower share leaves room for delays.
- Debt maturities. Is refinancing due while development is still unfinished?
- Power status of the pipeline. Which projects in the latest quarterly report depend on grid upgrades that haven't happened yet?
- Tenant concentration. Look at the share of revenue coming from the largest customers in the latest annual filing.
If you hold a broad real estate ETF instead, check how much of it is data centers before deciding any of this applies to you.
This post is for informational purposes only and does not constitute financial advice. Return figures from Stock Assembler's Compare Tickers tool (yfinance data), October 22, 2021 to October 22, 2026 and October 22, 2025 to October 22, 2026. NextDC figures from its October 21, 2026 ASX announcement as reported by Mingtiandi. Past performance does not guarantee future results.